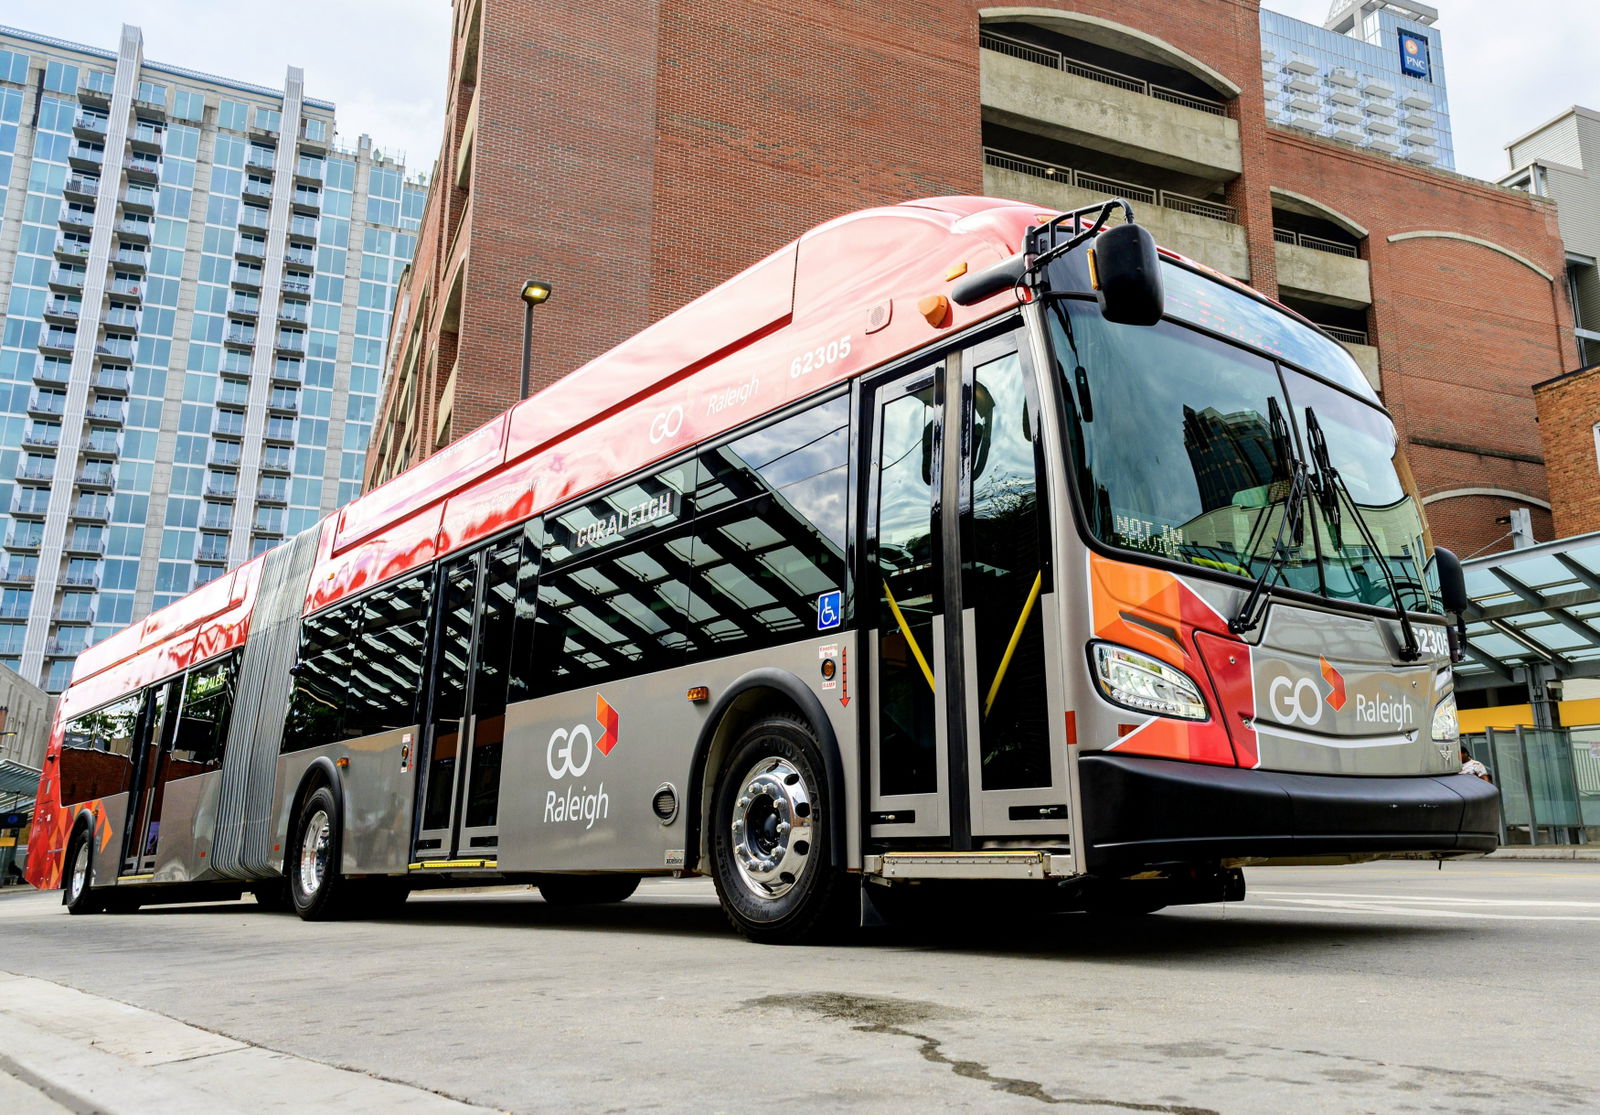
In New Flyer’s shadow: why is the US bus market awaiting a new competitor?
The North American bus market has undergone significant transformation in recent years. While the spread of electric vehicles has created new opportunities for manufacturers, the pool of potential suppliers has gradually narrowed, posing increasingly serious challenges for public transport operators. One of the biggest winners of this process has been New Flyer, which has become a dominant player in the US urban bus market, particularly in the articulated vehicle segment. However, the resulting situation is by no means necessarily favourable for customers. An official submission prepared by a San Francisco transport authority in September 2025, for example, points with unusual frankness to the consequences of limited competition, making it clear that it views Solaris’s North American entry not merely as a new procurement option, but as a potential means of strengthening market competition.
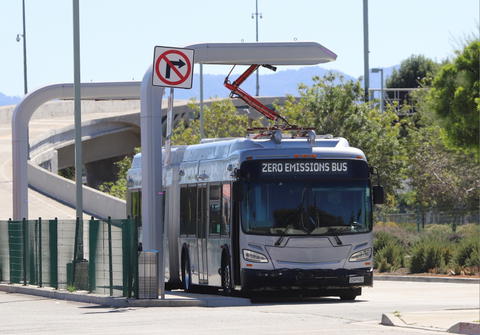
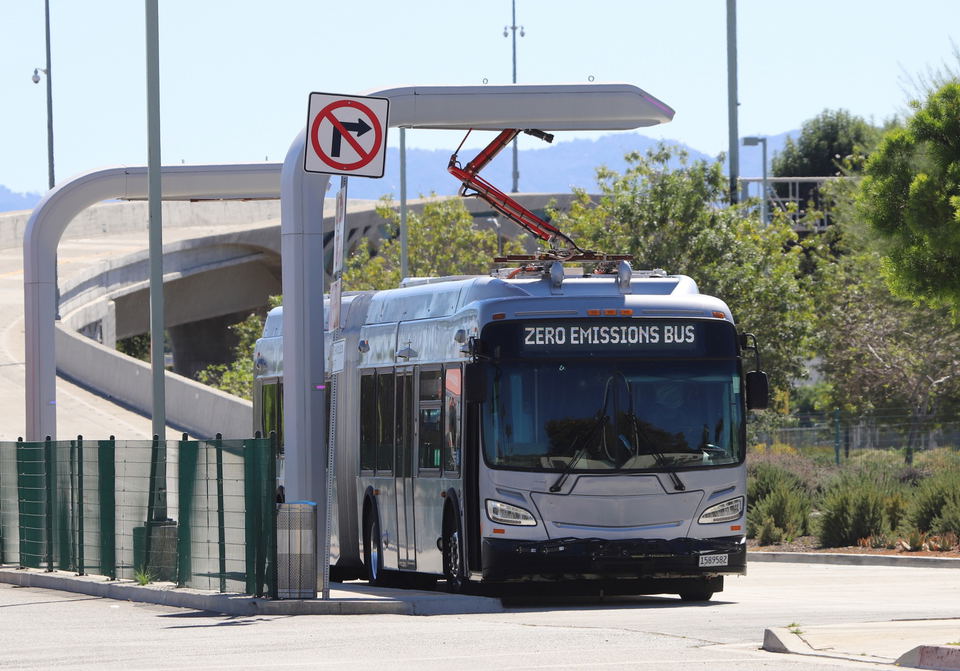
The San Francisco Municipal Transportation Agency’s (SFMTA) presentation of 3 September 2025 originally prepared the approval of the procurement of six Solaris electric buses. The contract was subsequently approved on 12 September. However, the document goes far beyond the particular order, as it also sets out in detail the market conditions that led the US transport authority to consider the involvement of a new European manufacturer justified. One of the most notable findings in the document was that New Flyer was at the time the only viable supplier of 60-foot, or approximately 18.3-metre, articulated buses, and that its vehicles were considered expensive. The SFMTA therefore explicitly set out to create competition among several manufacturers in future procurements, thereby reducing purchasing costs.
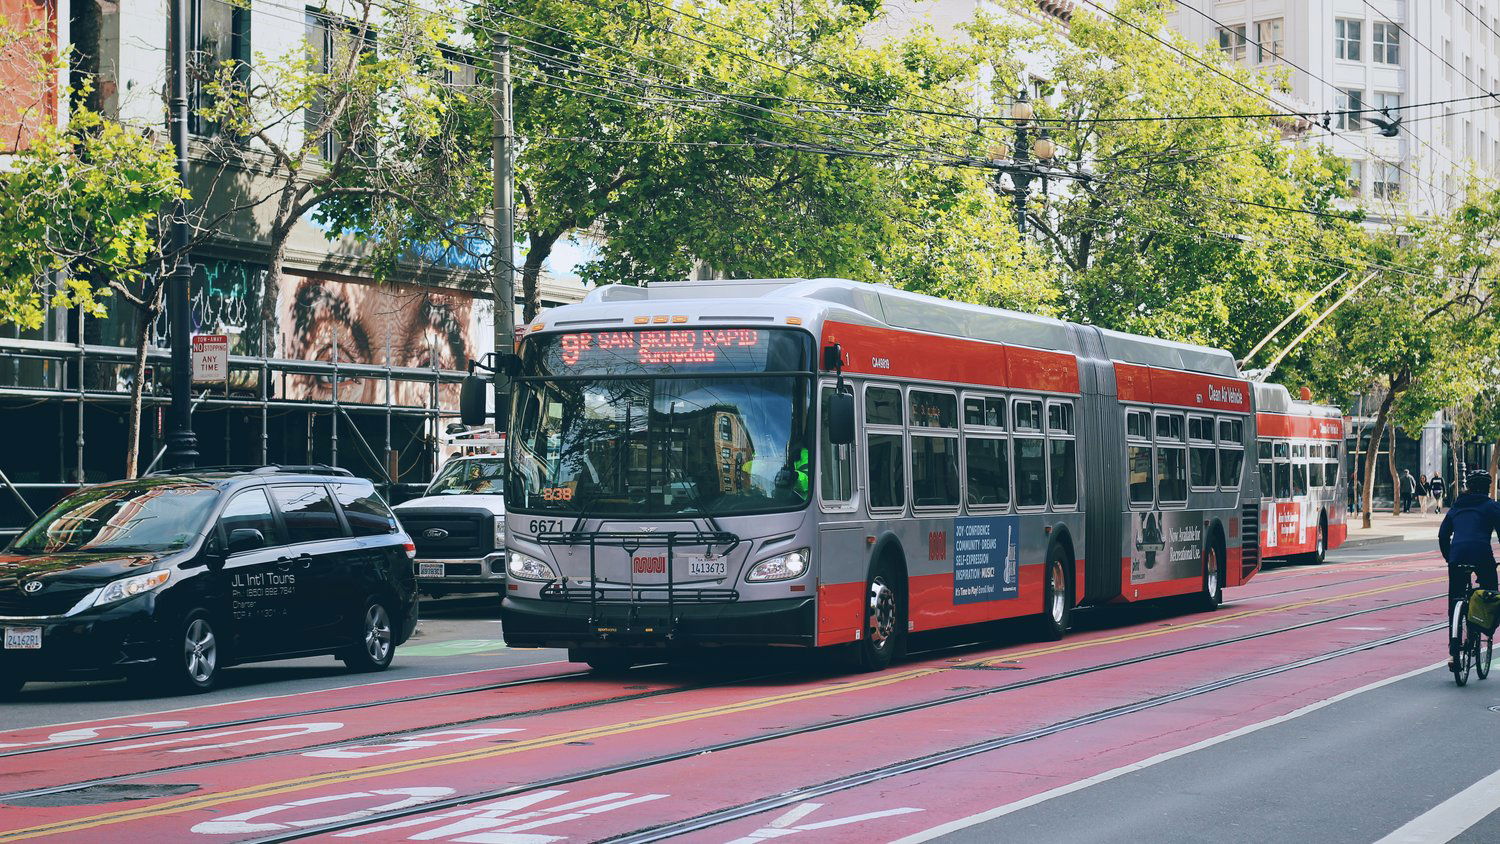
This finding is particularly noteworthy given that it is not criticism from a competitor or market analyst, but the assessment of its own position by a major US public transport operator. In essence, the authority acknowledged that the range of manufacturers available to it did not provide an adequate competitive environment, particularly in the market for high-capacity articulated electric buses.
A shrinking pool of manufacturers, growing dependence
The problems facing US bus manufacturing did not emerge overnight. Over the past decade and a half, the market has lost several major players, while the transition to electric propulsion has required companies to make ever greater investments in new production technologies and substantial development capacity. The situation has been further exacerbated by the consequences of the coronavirus pandemic, supply-chain disruptions and financial pressure on manufacturers.
Orion, formerly owned by Daimler, ceased bus production permanently in 2013, while Canadian manufacturer Nova Bus announced the phased discontinuation of its US manufacturing operations in 2023. The latter has not, however, withdrawn completely from the US market, as it can continue to serve US customers from its Canadian plants. Proterra’s 2023 bankruptcy proceedings and the subsequent sale of its bus manufacturing business also created uncertainty, while the earlier interruption of ElDorado National California’s (ENC) operations further narrowed the available range. ENC has since returned to the market under new ownership and, in September 2026, won an order from Los Angeles Metro for 220 electric buses worth approximately $337.7 million. This suggests that the range of US manufacturers may expand again, although an actual ramp-up in production capacity will also be required to restore the previous level of competition.
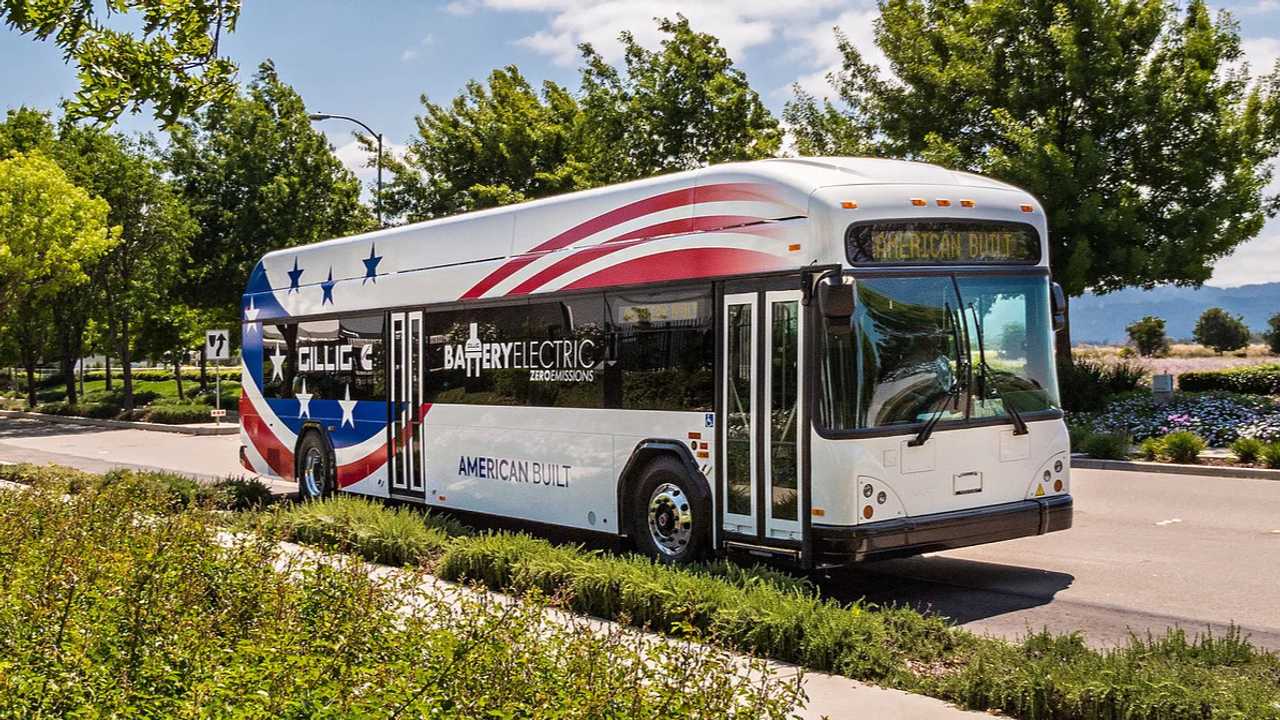
As a result of this process, New Flyer and Gillig have become the two dominant manufacturers in the market for US bus procurements supported by federal funding. The seriousness of the situation has also been examined by the United States Government Accountability Office (GAO). In a report published in 2025, it warned that the limited range of manufacturers could already jeopardise public transport operators’ fleet renewal programmes. Some operators anticipated delivery times of up to two years, which could make it particularly difficult to meet deadline-bound commitments relating to the electric transition.
According to data presented by the GAO, the estimated combined output of New Flyer and Gillig for 2024 was approximately 2,350 buses across all propulsion types. In the longer term, the two companies considered joint production of up to 4,800 vehicles per year possible, but this was an estimated potential capacity increase rather than an actually achieved production volume. The problem therefore stems not only from the scale of manufacturing capacity, but also from the fact that public transport operators have extremely few alternatives to choose from.
New Flyer is in a particularly strong position
New Flyer’s market position has been strengthened not only by its own production capacity, but also by the previous consolidation of the North American bus industry. One key milestone was the 2013 acquisition of the Hungarian-rooted North American Bus Industries (NABI), a move that New Flyer’s then President and Chief Executive Officer, Paul Soubry, said the company had pursued for a long time. Acquired for approximately $80 million, NABI still had substantial production capacity and an extensive customer base at the time: in the twelve months preceding the acquisition, it had sold 582 bus-equivalent vehicles, while its order backlog amounted to 1,579 bus equivalents, including 593 firm orders. Since its reorganisation in 1992, the company had sold several thousand buses, and approximately 7,500 NABI vehicles were operating on North American roads at the time of the acquisition.
Although New Flyer initially emphasised the alignment of the two companies’ product ranges, more efficient utilisation of production capacity and an expanded customer base when announcing the transaction, subsequent developments made it clear that the acquisition would also eliminate the former competitor’s independent market presence. Barely a year later, in June 2014, the phased withdrawal of NABI’s own bus types was announced, together with the conversion of the Anniston, Alabama plant to produce New Flyer’s Xcelsior model range. The Canadian manufacturer thus gained not only substantial production capacity and new customers, but also saw an independent competing brand disappear from the North American bus market.
However, New Flyer did not achieve its dominant role solely through acquisitions. Over decades, the company has built up a manufacturing, parts supply and service network, and its vehicles play a prominent role in numerous major urban transport systems. Its product range extends from diesel, natural-gas and hybrid buses through trolleybuses to battery-electric and hydrogen-powered models, while it has built a particularly strong position in the articulated electric bus segment.
From the customer’s perspective, however, this situation has a dual nature. The presence of a large, experienced manufacturer may mean a more predictable technical support framework and long-term parts availability, but the absence of competitors can reduce scope for price negotiation and increase dependence on a single supplier.
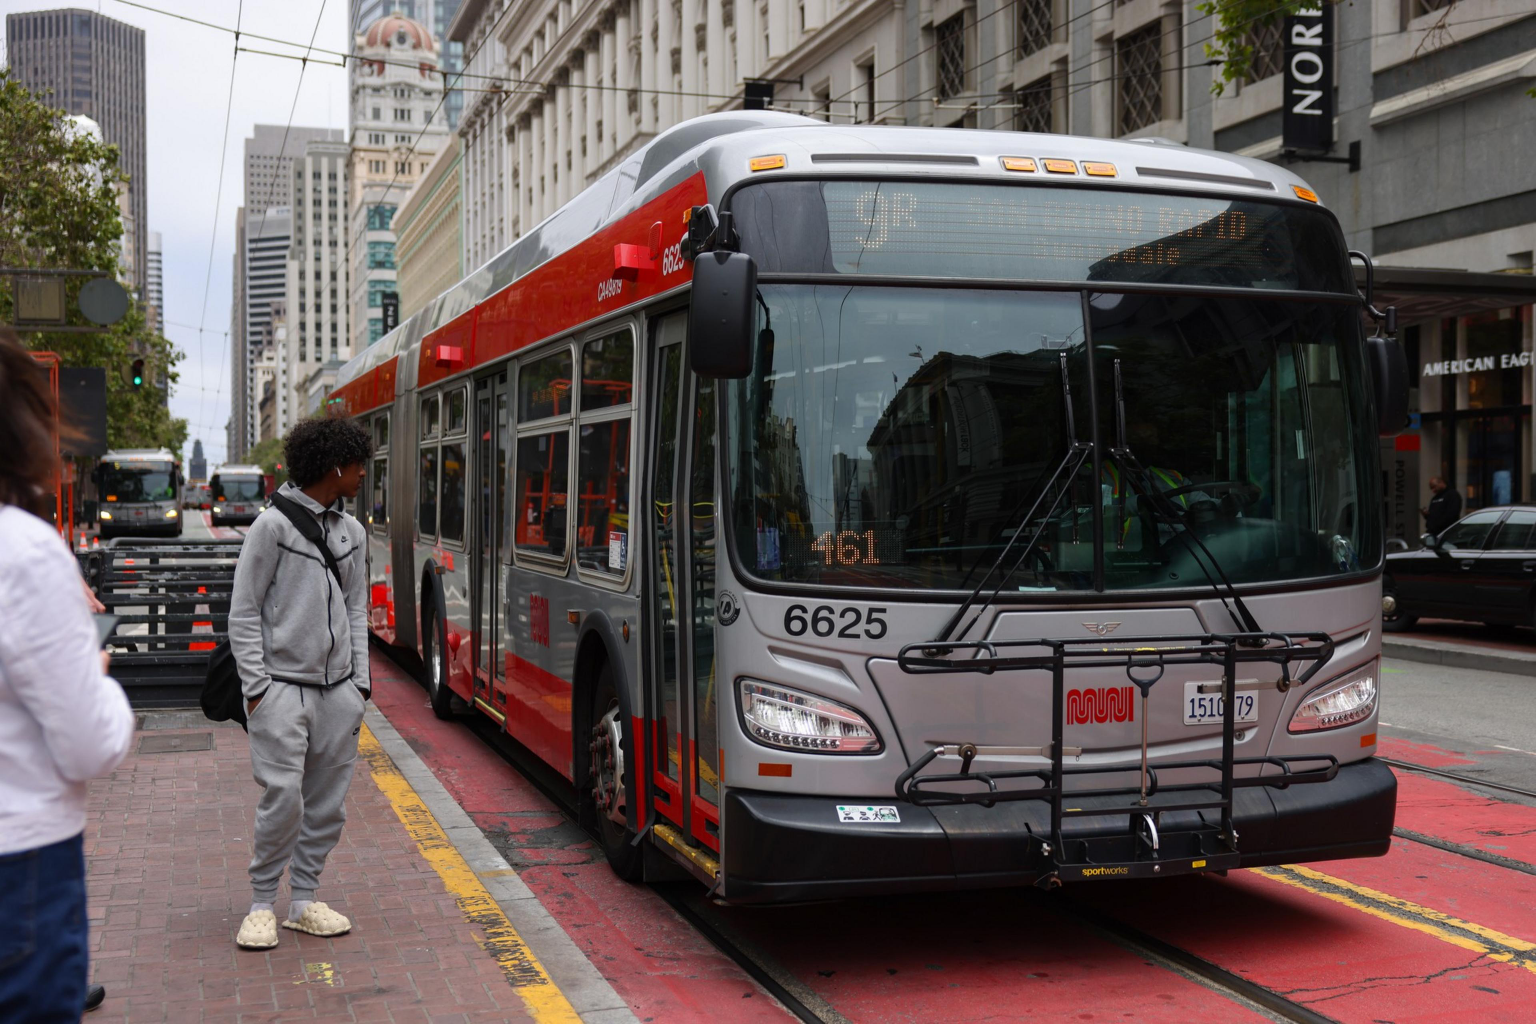
San Francisco provides a particularly illustrative example. According to information presented at the SFMTA’s meeting in September 2025, approximately 90% of the city’s bus fleet consisted of New Flyer vehicles at the time. The authority therefore relied heavily on the same manufacturer not only for new procurements, but also for maintaining its existing fleet.
Lack of competition is not the only reason behind high prices
Rising prices for US buses are, however, a more complex phenomenon than can be explained solely by supplier concentration. Public transport operators often impose extremely detailed technical requirements on manufacturers, which can differ significantly from one another. Even within fundamentally identical vehicle categories, they may specify different passenger-compartment layouts, on-board equipment, electronic systems and other components, making cost-effective production based on larger series more difficult.
Such production based on bespoke specifications places additional burdens on suppliers, may increase development and manufacturing costs, and can lengthen delivery times. Added to this are the costs of electric drivetrains, battery systems and the necessary safety equipment, as well as expenses arising from compliance with US manufacturing and procurement requirements.
San Francisco is deliberately seeking to broaden its supplier base
San Francisco’s transport authority (SFMTA) has launched a fleet renewal programme aimed at replacing 112 ageing hybrid buses, under which it decided to procure 94 new hybrid and 18 battery-electric vehicles. While the hybrid buses were ordered from New Flyer, three manufacturers were included for the electric buses. New Flyer is represented by seven vehicles, Gillig by five and Solaris by six. Procurement involving several suppliers provides an opportunity to compare different makes, while reducing the transport authority’s dependence on a single manufacturer.
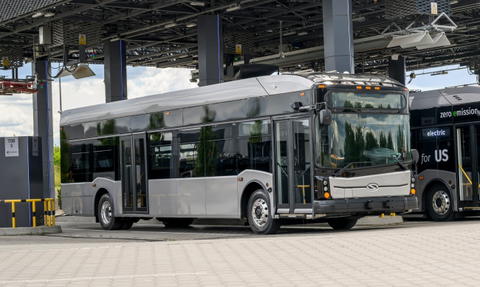
The Solaris order approved in September 2025 covers three standard-length and three articulated electric buses. The procurement is based on a framework agreement established by King County Metro in the Seattle area, which may also be used by other US public transport operators. King County Metro itself ordered four Solaris electric buses, two standard-length and two articulated vehicles. For San Francisco, however, the six vehicles primarily represent an opportunity to assess the Polish manufacturer’s products under its own operating conditions and to take into account a further supplier that has been genuinely tested in subsequent procurements.
Buy America is both an obstacle and an opportunity
One of the biggest barriers to entering the US bus market is the Buy America requirement system associated with federal funding. For subsidised vehicle procurements, the regulations require a specified proportion of US value added and final assembly in the United States. In the case of buses financed through federal transport grants, this means at least 70% US content and domestic final assembly.
In practice, this means that a European manufacturer cannot become a generally accessible supplier for bus procurements financed from federal funds merely through export activity. The San Francisco procurement was therefore carried out under a particularly interesting arrangement. The city did not use federal funding to purchase Solaris vehicles, meaning that the contract was not subject to federal Buy America requirements.
According to a report by San Francisco’s Budget and Legislative Analyst’s Office, Solaris was also unable to take part in the city’s earlier electric bus trial programme because it was federally funded. The new procurement therefore created an entry opportunity for the European manufacturer that had not been available under the earlier programme.
The arrangement also involved risks, however. The 2025 submission specifically addressed potential changes in US tariff policy and allowed for contract prices to be adjusted, the quantity ordered to be reduced, or, in extreme cases, the agreement to be terminated without cost. The authority and the manufacturer intended to review the effects of the current tariff environment three months before production began.
Solaris has also made progress in preparing US manufacturing: based on CAF’s plant in Elmira, New York State, the company has already established the initial foundations for local production. While the first buses ordered for Seattle and San Francisco will still be built in Poland, the US production base is intended to play a role in fulfilling subsequent US orders. This is particularly important in terms of complying with Buy America requirements applied to federally funded procurements.
The trolleybus market is also a strategic opportunity for Solaris
One of the most interesting parts of the San Francisco document is that it does not justify Solaris’s involvement solely through the procurement of battery-electric buses. The SFMTA specifically drew attention to the European manufacturer’s trolleybus production experience, which it considers valuable for the North American market in the longer term as well.
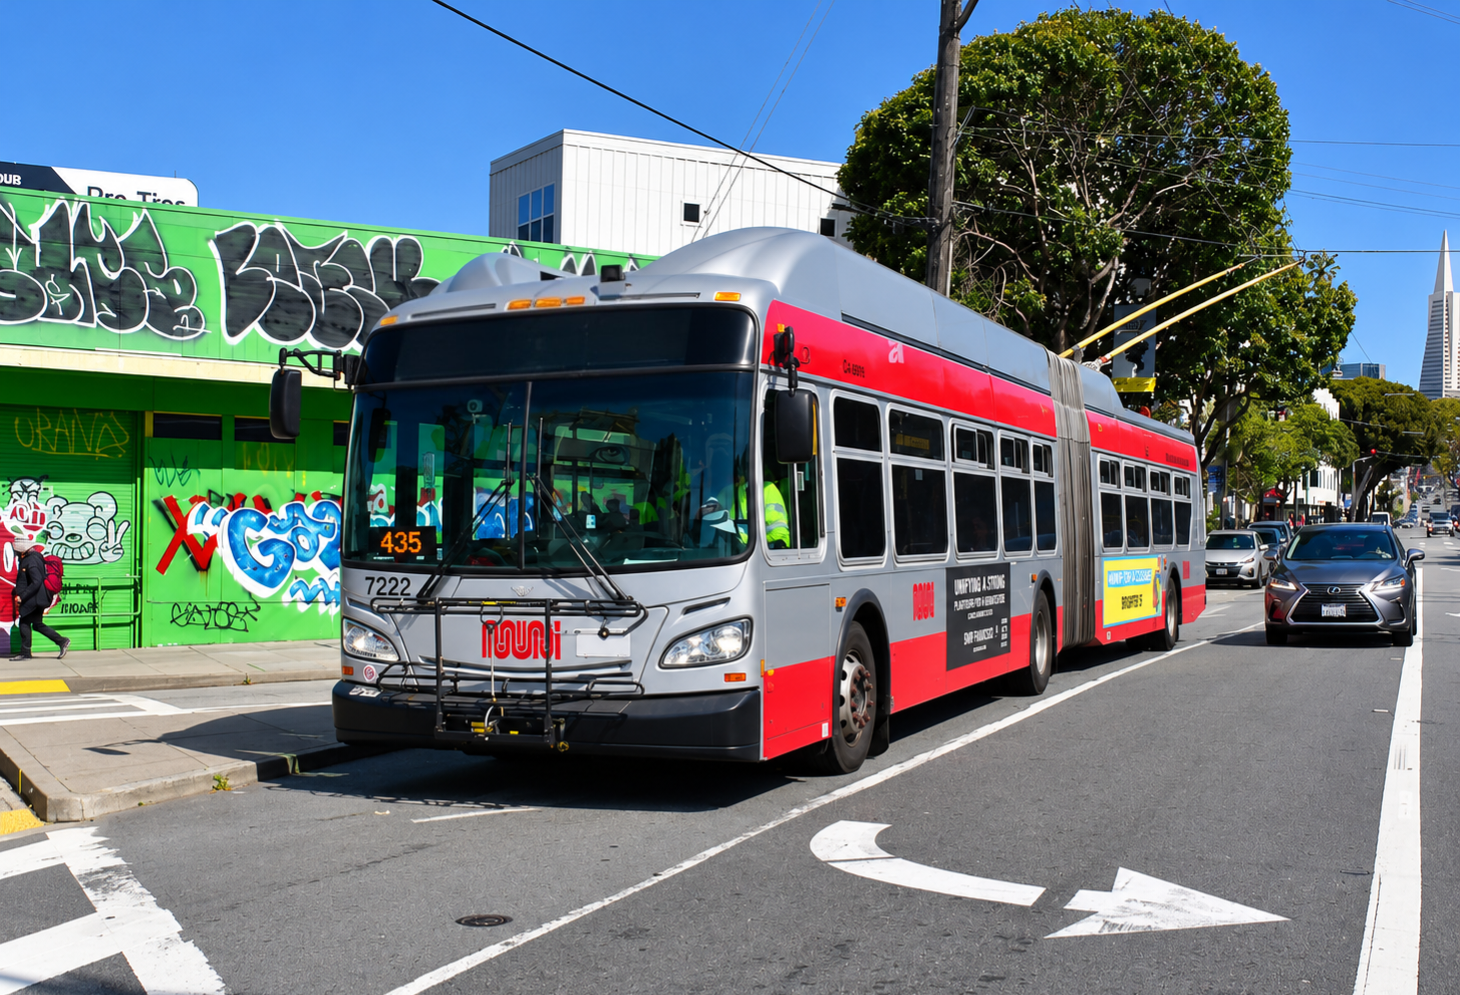
San Francisco is among the few major US cities that still operate an extensive trolleybus network. The city intends to retain the technology in the future and is examining potential applications of so-called In Motion Charging (IMC) systems based on charging batteries while in motion. This is a particularly favourable circumstance for Solaris, as it has gained substantial experience in the European market in the development and manufacture of both conventional trolleybuses and those capable of off-wire operation.
The authority’s budget analysis went even further. According to the document, San Francisco is also interested in establishing a relationship with Solaris because the European manufacturer could represent a potential alternative if the current supplier, New Flyer, were to withdraw from the trolleybus market in the future. This does not, of course, mean that New Flyer has made such a decision, but rather that the transport authority wishes to secure other options in order to mitigate supplier risks.
Solaris’s position in this area could also be strengthened by the Vancouver trolleybus programme. The procurement under way in the Canadian city, involving 275 vehicles, could provide the Polish manufacturer with a significant North American reference. In the case of trolleybuses, Solaris is not attempting to enter the market with an entirely new technology, but with a product category in which it already has decades of European experience.
This is also important because the trolleybus market is even narrower than that for battery-electric buses, so the arrival of a new manufacturer with suitable references could be of particular significance.
Solaris must contend with more than just New Flyer
Solaris must also address issues that are less prominent in the European market. In the United States, public transport operators often plan for long operating lives, specific technical requirements and extensive local parts supply. For customers, therefore, not only the vehicle’s purchase price but also whole-life maintenance costs, repairability, security of parts supply and the manufacturer’s long-term presence are decisive.
The picture is further complicated by the fact that the US bus market’s electric transition is not progressing at a uniform pace. High purchase costs, financing uncertainties and operational experience may lead some public transport operators to review their earlier electrification plans. This also poses a risk for Solaris, as all-electric buses are at the centre of the manufacturer’s North American offering.
At the same time, it is precisely this uncertain environment that may create an opportunity for a new supplier. It may become increasingly important for US customers not to depend exclusively on the production capacity, pricing and business decisions of only one or two manufacturers. The arrival of a new player can have a beneficial effect on the market even if it initially fulfils only relatively small orders, since the very prospect of competition can improve public transport operators’ negotiating position.
It is not about ten buses
While European bus manufacturers are facing increasingly fierce competition in their home market, primarily from China, it is precisely the lack of competitors in the United States that could create new opportunities for them. The problems facing the two markets are therefore substantially different, yet they can be traced back to the same fundamental question: how can healthy competition and an adequate range of manufacturers be ensured in the long term?
Solaris’s greatest challenge, therefore, is not necessarily whether it is capable of producing competitive buses from a technical standpoint. Its European experience suggests that it is. The crucial question is rather whether, by adapting to the US regulatory and market environment, it can establish a local manufacturing, sales and service network that will make it a lasting alternative alongside New Flyer and Gillig. The industrial and financial strength of the Spanish CAF Group behind it could provide a significant advantage in this respect. The Hungarian-rooted NABI, after all, did not have the backing of a similarly sized international group specialising in the manufacture of transport vehicles, and although the company had substantial manufacturing capacity and a customer base, it ultimately proved unable to counter New Flyer’s increasingly strong market position and expansion. Solaris may be in a more favourable position in this regard: with CAF’s support, it can draw on industrial and financial resources that could give it a long-term chance of competing with the leading players in the North American market.